JavaScript is required to view this site.
Please enable JavaScript and reload the page.

05 Strategy & Vision

The long view, and what it costs to hold it.

A strategic reading of the luxury sector: where value is actually created, why it accumulates slowly, and which decisions determine a house's position a decade after they are taken.

Format
Six strategic questions, examined in sequence
Framing
Industry analysis prepared for this website
Attribution
Not presented as the views of Francesca Bellettini
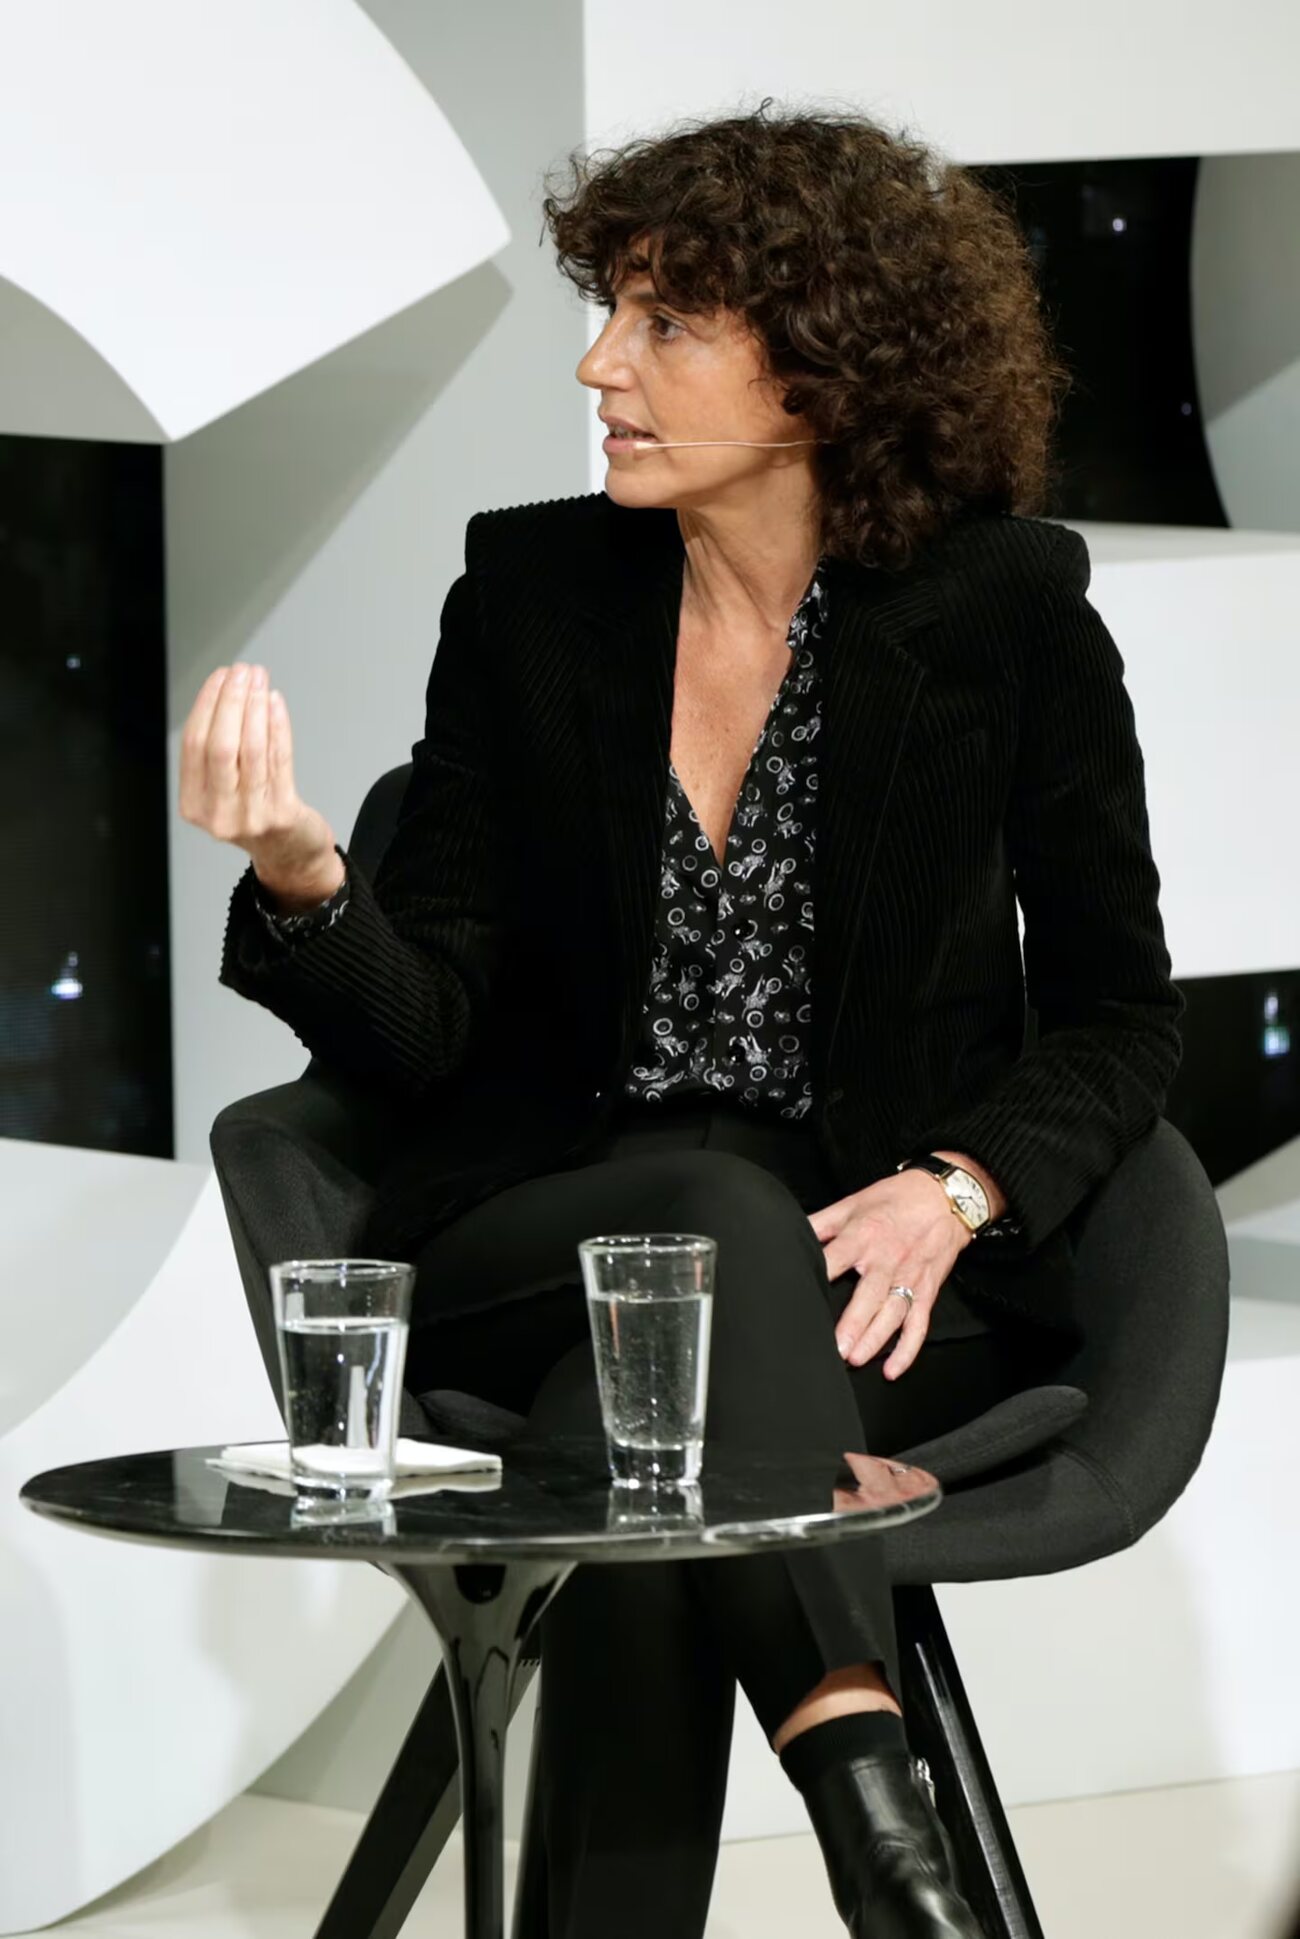
Francesca Bellettini seated in conversation in a contemporary interior
In conversation

Strategy in luxury is mostly a question of what compounds.

Most industries reward the efficient conversion of investment into output. The luxury sector rewards something less tractable: the accumulation of meaning. A house's ability to price above its material cost, to hold that price through economic cycles, and to be sought rather than sold, rests on an asset that no balance sheet captures well and no quarter can create.

This produces a peculiar strategic environment. The activities that build the asset — consistency, restraint, craft, patience, coherence across every point of contact — are slow and largely invisible in short-run performance. The activities that spend it — extension, discounting, widened distribution, accelerated output — are fast and immediately visible in revenue.

A strategy in this sector is therefore best judged by what it protects rather than by what it promises. The six questions that follow are the ones that seem to determine, over a decade, whether a house has been built or drawn down.

SlowIdentity, standards, craft — the assets that compound
FastDistribution, communication, service — the layers that must adapt
HeldPrice architecture and codes — changed rarely and deliberately
SpentExtension and volume — measurable now, costly later

The Questions

Six decisions that set a house's position for a decade.

None of these can be settled by data alone, and none can be settled by taste alone. Each is a judgement about identity made under commercial constraint.

I

What is this house actually for?

The question sounds elementary and is answered badly more often than any other. A house's purpose is not its category, its founder's biography or its current aesthetic. It is the reason a customer would choose it over a competitor whose product is comparable in quality and price.

Answers that survive contact with the market tend to be narrow and slightly uncomfortable, because a genuine position excludes people. Answers that fail tend to be expansive and agreeable — the kind that no one in the organisation objects to, and that consequently constrain nothing.

The practical test is whether the answer generates refusals. If a stated purpose has never caused a house to decline a profitable opportunity, it is probably a description rather than a strategy.

II

Where does the price architecture begin and end?

Price in luxury is not primarily a mechanism for capturing willingness to pay. It is a statement about what a house believes itself to be, and customers read it as such. The architecture — the entry point, the core, the upper range and the distance between them — is one of the most consequential structures a house maintains.

The pressures on it are constant and asymmetric. An accessible entry point recruits new customers and generates volume; extended too far downward it redefines the house in the mind of the market. An elevated upper range asserts capability and craft; unsupported by genuine substance it reads as arbitrage.

The strategic discipline is to decide the architecture deliberately and then to defend both ends of it — recognising that pressure will come predominantly from below, in the form of reasonable-sounding proposals to widen access.

III

How much distribution is enough?

Distribution is where the tension between growth and scarcity becomes concrete. Every additional point of sale adds revenue and subtracts, marginally, from the sense that the house is difficult to obtain. The subtraction is not visible in the period in which it occurs.

The decision has become more complex as the boundary between channels has dissolved. A house's own stores, its digital platform, department stores, multi-brand retail, travel retail and the resale market together determine how available it feels — and the last of these is largely outside its control.

What appears to distinguish durable positions is a willingness to treat distribution as a defined limit rather than an open variable: a stated view of where the house should be present and, more importantly, where it should not.

IV

Which markets deserve concentration rather than coverage?

International expansion in luxury is frequently discussed as coverage — the number of markets in which a house is present. Concentration is usually the better frame. Depth in a market produces client relationships, cultural legitimacy and pricing power; breadth without depth produces presence and little else.

Concentration is expensive and slow. It requires retail investment, local leadership of genuine quality, patience through the period in which a market does not yet return its cost, and a willingness to be less visible elsewhere in the meantime.

The judgement is which markets justify that commitment for this particular house — a question that has to be answered specifically, because the answer differs between houses whose positions and customer bases differ, even within the same group.

V

How is creative authority structured?

Where creative authority sits, how far it extends, and what it is accountable for are structural decisions with commercial consequences that persist for years. They determine coherence across product, image, retail environment and communication — and coherence is most of what distinguishes a house with an identity from a company with a logo.

Two failure modes recur. Authority that is too narrow produces a house whose product is considered and whose stores, campaigns and digital presence belong to a different sensibility. Authority that is too broad produces a house that cannot function without one person and has no answer to their eventual departure.

The related question — what creative leadership is accountable for, and on what timescale — is asked less often than it should be. Holding creative work to commercial account is legitimate; holding it to account on a quarterly cycle produces work designed to survive the quarter.

VI

What is the house's relationship to its own past?

Heritage is among the few genuinely non-replicable assets in the sector. A competitor can match a material, a price or a store location; it cannot manufacture a hundred years of accumulated association. But heritage generates value only when it is used, and using it means interpreting it — which necessarily means changing it.

Houses that treat the archive as sacred tend to produce work that is respectful and inert. Houses that treat it as a resource to be mined tend to exhaust it, converting a long-duration asset into a series of short-duration references.

The workable position lies between: a clear internal understanding of which elements are load-bearing and must persist, and which are period detail that can be reinterpreted or set aside. Arriving at that understanding is a matter of judgement, and it is one of the few strategic questions in luxury for which no analytical method exists.

Industry Context General strategic analysis of the luxury sector, prepared for this website. It does not describe, imply or disclose the strategy, plans or internal decisions of Gucci, Kering or any other company, and is not attributed to Francesca Bellettini.

Vision

A vision in this industry is not a statement about the future. It is a decision about which things will not be traded for the present.

Editorial analysis prepared for this website.

01

Clarity over ambition

Ambition is abundant in luxury and rarely differentiating. Clarity about position, customer and limit is scarce, and it is what allows an organisation to act consistently when the reasoning is not restated.

02

Coherence over campaign

A memorable campaign moves a season. Coherence across product, retail, service and image moves a decade. The second is harder to produce, harder to observe and considerably more durable.

03

Capability over announcement

Direction announced before the organisation can deliver it creates a gap that the market reads accurately. Building capability first is slower, less satisfying to describe, and the sequence that holds.

Continue

How brands are built, and what they are built from.

Contact
Mr. Digant Sharma